Money after 55
Claiming Social Security at 62, 67 or 70: how the math works
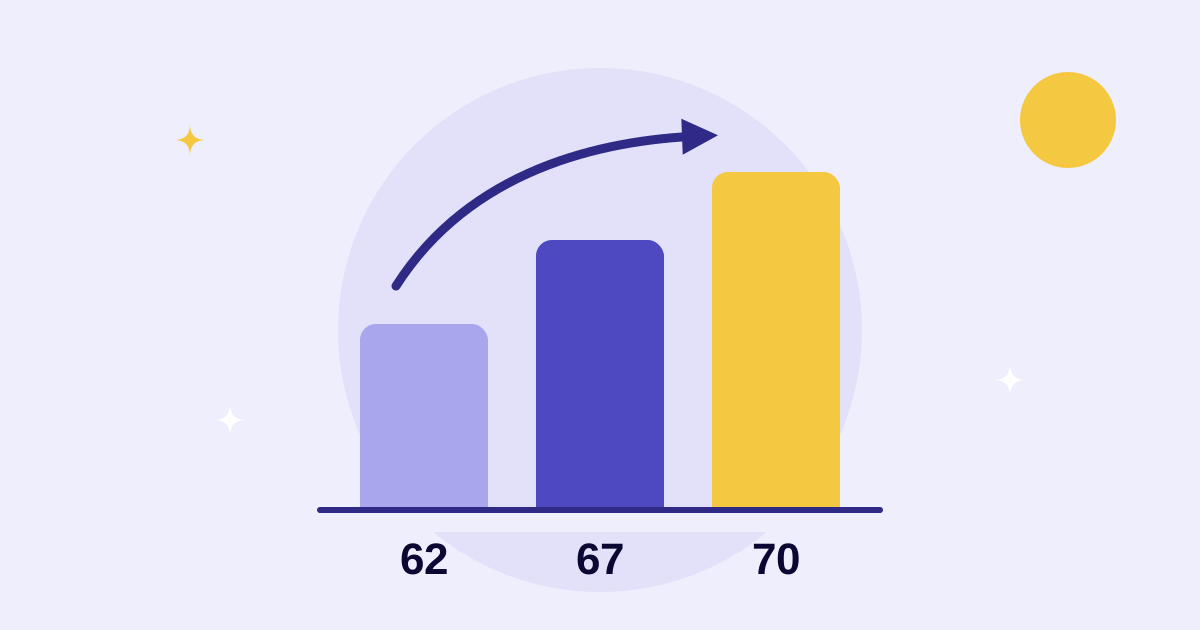
Claiming at 62 can cut your check by 30% for life; waiting until 70 raises it 24%. A worked example, breakeven ages and the 2027 earnings limits.
The years around retirement bring a few decisions that are hard to undo, like when to claim Social Security and how to draw down your savings.
Claiming at 62 can cut your check by 30% for life; waiting until 70 raises it 24%. A worked example, breakeven ages and the 2027 earnings limits.
This page is general information, not personal financial advice. Terms and rates change, so confirm details with any provider before you apply.